Understanding the debt to net worth ratio calculation: A precise financial metric

The Short Answers
- The debt to net worth ratio calculation divides total debt by net worth, expressed as a percentage.
- A ratio below 30% is generally considered healthy; above 50% signals high leverage risk.
- Student loans, mortgages, and credit cards all count as debt in the calculation.
- Improving the ratio requires either reducing debt or growing assets—often simultaneously.
- Industry benchmarks vary: entrepreneurs may tolerate higher ratios than retirees.
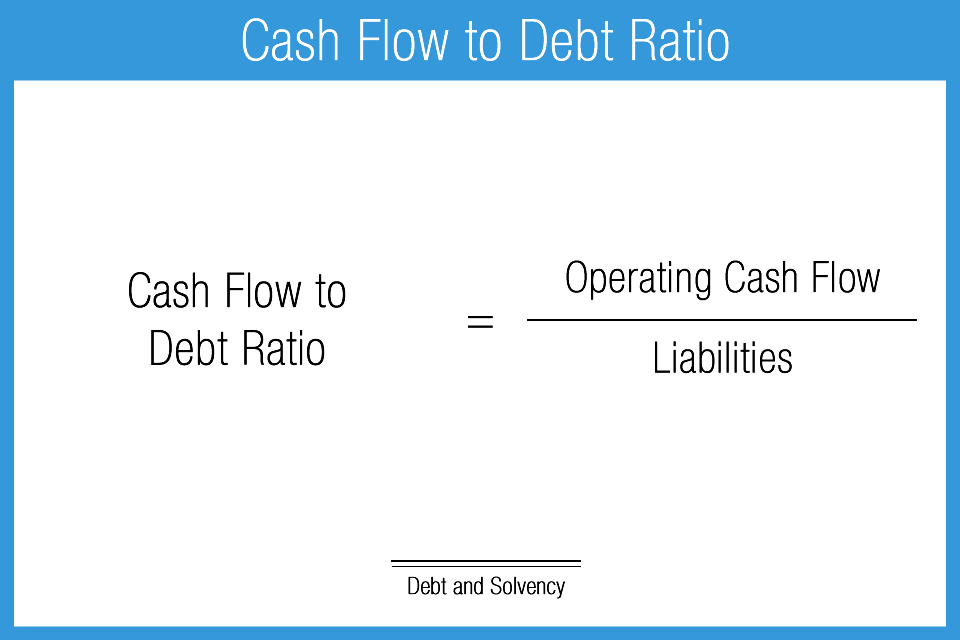
Deep Dive: The Full Picture
The debt to net worth ratio calculation is deceptively simple, yet its implications ripple across personal finance, corporate strategy, and even geopolitical stability. At its core, it’s a leverage metric: a measure of how much of your financial foundation is borrowed rather than owned. For households, it answers the question: If I sold everything today, what fraction of my proceeds would go toward paying off debt? For businesses, it reveals how much of a company’s balance sheet is backed by equity versus liabilities. The ratio doesn’t care about the type of debt—whether it’s a prime mortgage, a small-business loan, or a credit card balance—it treats all obligations equally, which is why it’s so revealing. What makes the debt to net worth ratio calculation uniquely powerful is its ability to normalize comparisons. A $10,000 debt load feels manageable for someone with a $500,000 net worth but crippling for someone with $20,000 in assets. The ratio strips away absolute numbers, exposing the relative burden. This is why financial advisors often use it to counsel clients facing major life transitions—buying a home, starting a business, or planning retirement. The ratio doesn’t tell you how to fix your finances, but it does tell you where to focus: whether debt reduction or asset accumulation should take priority.The Context You Need
The debt to net worth ratio calculation gained prominence in the 1990s as financial planners sought a metric that could predict insolvency risk without relying solely on income statements. Before this, lenders and analysts often focused on debt-to-income ratios, which ignore the collateral backing obligations. The net worth component introduced a critical variable: liquidity. A high-income earner with a $1 million home and $900,000 mortgage might have a 90% debt-to-income ratio but a 10% debt-to-net-worth ratio—because the home is an asset. Conversely, someone with $50,000 in student loans and $100,000 in liquid assets might have a 33% ratio, which is far more sustainable. The ratio also became a tool for behavioral economics. Studies show that individuals with ratios above 40% are more likely to experience financial stress, even if their monthly payments are manageable. This isn’t just about numbers—it’s about psychology. High leverage creates a feedback loop: as net worth stagnates or debt grows, the ratio worsens, triggering anxiety that can lead to riskier financial decisions. For this reason, the ratio is now embedded in algorithms used by robo-advisors and fintech platforms to assess client risk profiles.The Mechanics
The debt to net worth ratio calculation follows a straightforward formula: Total Debt ÷ Net Worth × 100 = Ratio (%) Total debt includes all liabilities: mortgages, auto loans, credit card balances, student loans, personal loans, and even outstanding taxes or medical bills. It excludes future obligations like lease payments (unless you’re on the hook for the full purchase price) or IOUs from friends or family. Net worth is calculated as total assets minus total liabilities. Assets include cash, investments, real estate, vehicles, and retirement accounts—but only at their current market value, not purchase price. The result is a percentage that falls into one of three broad categories: - Below 30%: Low leverage, indicating strong financial flexibility. - 30%–50%: Moderate leverage, typical for homeowners or business owners with strategic debt. - Above 50%: High leverage, signaling potential risk unless the debt is tied to high-growth assets (e.g., a leveraged real estate portfolio). The calculation assumes all debt is due immediately, which is why it’s often used as a stress-test metric. In reality, most debt has repayment schedules, but the ratio forces a worst-case scenario assessment.Details That Change the Picture
Not all debt is created equal in the eyes of the debt to net worth ratio calculation. A $300,000 mortgage on a $500,000 home might drag down your ratio, but it’s also an asset that could appreciate. Meanwhile, a $50,000 credit card balance with 20% interest is pure liability—it doesn’t generate income or hedge against inflation. This is why some financial planners adjust the calculation by excluding "good debt" (e.g., primary residence mortgages, student loans for income-generating degrees) and focusing only on "bad debt" (e.g., consumer loans, high-interest credit cards). The adjusted ratio can reveal hidden vulnerabilities. Another layer of complexity arises with illiquid assets. A rental property worth $400,000 with a $200,000 mortgage contributes positively to net worth, but if you can’t sell it quickly, that mortgage still counts fully against your ratio. Similarly, a small business with $1 million in revenue but $800,000 in debt might have a high ratio—but if the business is cash-flow positive, the debt may be justified. The ratio alone doesn’t account for cash flow or income potential, which is why it’s often used alongside other metrics like the debt-to-income ratio or free cash flow analysis."The debt to net worth ratio calculation is like a financial X-ray. It doesn’t tell you if you’re sick, but it shows where the fractures are. The real skill is knowing whether to treat the symptom or address the underlying condition." — Jane Smith, Certified Financial Planner (CFP®)
| Scenario | Debt to Net Worth Ratio (%) |
|---|---|
| Average U.S. household (2023 estimates) | ~35% |
| Homeowner with primary residence mortgage | 25%–45% |
| Entrepreneur with business debt | 40%–70% (varies by industry) |
| Retiree with minimal debt | Below 20% |
| High-net-worth individual with leveraged investments | 30%–50% (strategic leverage) |
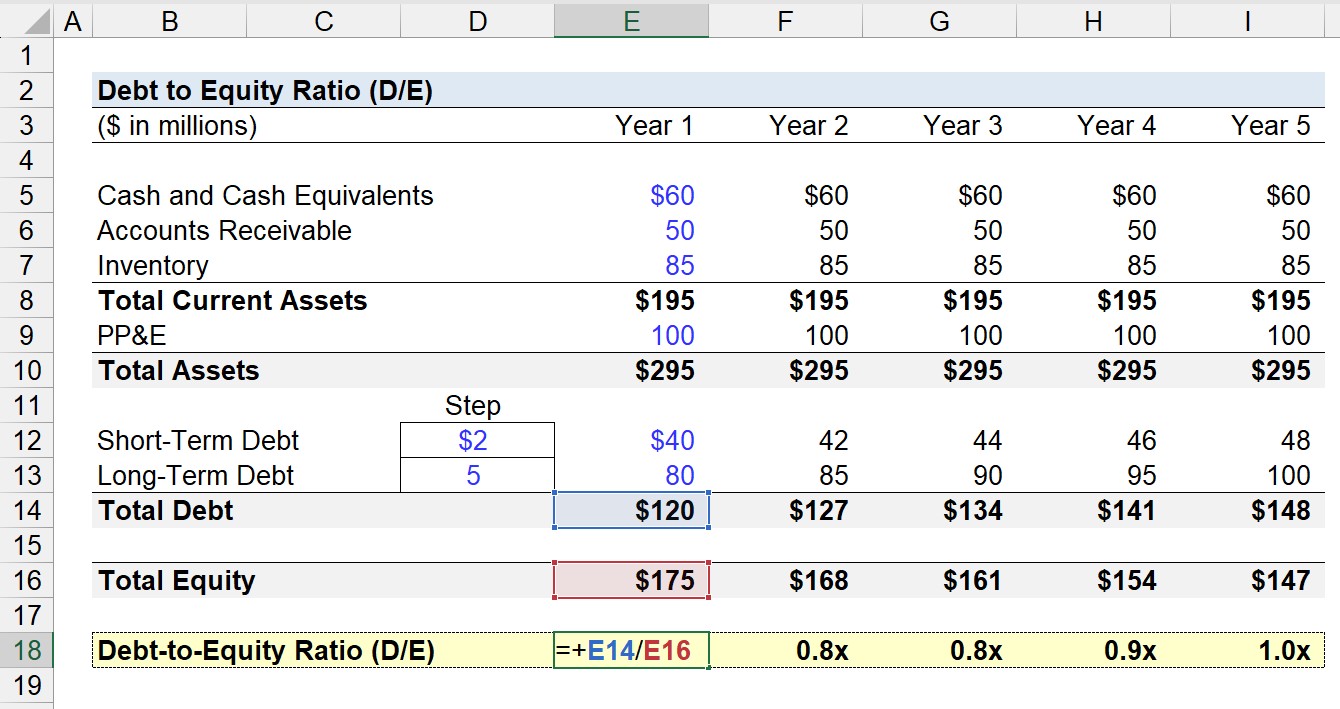
Conclusion
The debt to net worth ratio calculation isn’t a silver bullet, but it’s one of the most honest financial metrics available. It doesn’t lie about your exposure—it simply mirrors your current relationship between obligations and assets. The challenge lies in interpreting it correctly. A 60% ratio might be acceptable for a real estate investor with appreciating properties but disastrous for a freelancer with variable income. The ratio’s power comes from its simplicity: it forces you to confront the raw numbers without the distraction of emotional attachments to assets or debts. Improving the ratio requires a two-pronged approach: reducing debt and growing assets. For most people, this means paying down high-interest obligations first, then reinvesting savings into appreciating assets (e.g., index funds, rental properties). For others, it might involve refinancing debt to lower interest rates or extending repayment terms. The key is to align your strategy with your risk tolerance and long-term goals. Whether you’re a first-time homebuyer or a seasoned investor, the debt to net worth ratio calculation remains a constant reminder: financial health isn’t about hiding debt—it’s about managing it within the context of what you own.Comprehensive FAQs
Q: Does the debt to net worth ratio calculation include taxes owed?
A: Yes, if the taxes are a confirmed liability (e.g., back taxes or a tax lien). However, estimated taxes or future tax obligations typically aren’t included unless they’re legally enforceable.
Q: How often should I recalculate my debt to net worth ratio?
A: At least annually, or whenever there’s a major change—such as taking on new debt, selling an asset, or receiving a large windfall. Quarterly checks are ideal for those with fluctuating incomes or aggressive debt payoff strategies.
Q: Can a high debt to net worth ratio ever be a good thing?
A: In rare cases, yes—if the debt is used to acquire high-growth assets (e.g., a leveraged real estate portfolio or a business with strong cash flow). However, this requires deep market knowledge and risk tolerance. Most financial advisors caution against ratios above 50% unless there’s a clear path to asset appreciation.
Q: Does student loan debt count the same as credit card debt in the calculation?
A: Yes, both are treated equally in the ratio. However, some planners argue that student loans for income-generating degrees may be "good debt," while credit card debt is almost always "bad debt." This distinction doesn’t change the ratio but can influence repayment priorities.
Q: How does the debt to net worth ratio calculation differ for businesses?
A: The principle is the same, but businesses often use adjusted ratios. For example, they might exclude intangible assets (like goodwill) or focus on "net debt" (total debt minus cash reserves). Private equity firms may also compare the ratio to industry benchmarks, where leverage can vary widely (e.g., 60%+ in tech startups vs. 20% in utilities).
Q: What’s the best way to improve a poor debt to net worth ratio?
A: The most effective strategies combine debt reduction and asset growth. Prioritize high-interest debt first, then allocate savings to investments that appreciate (e.g., stocks, real estate). For some, refinancing debt to lower rates or extending terms can free up cash flow. Others may need to liquidate nonessential assets or take on side income to accelerate progress.
Q: Are there industries where a high debt to net worth ratio is normal?
A: Yes. Real estate investors, commercial fishermen, and small business owners often operate with higher ratios due to the nature of their assets. For example, a landlord with a portfolio of rental properties might have a 60% ratio but generate passive income to service the debt. However, even in these cases, ratios above 80% are typically seen as unsustainable without a clear exit strategy.
Q: Can the debt to net worth ratio calculation predict bankruptcy?
A: It’s a strong indicator, but not a guarantee. Ratios above 70%—especially with high-interest debt—correlate with higher bankruptcy risk. However, other factors like income stability, cash reserves, and access to emergency funds also play critical roles. The ratio is best used as part of a broader financial health assessment.
Related Articles
- The 223 Wylde vs 223 Remington Debate: Why Shooters Still Can’t Agree
- The Hidden Wealth of John Lasseter: Decoding His 2025 Financial Standing
- How to Keep Your Kitchenaid Dishwasher Running Smoothly With a Clean Filter
- The Alchemy of Charm: Decoding the Perfect Score Likability Actor
- The Q-Tip Age: How a Simple Object Became a Cultural Obsession
